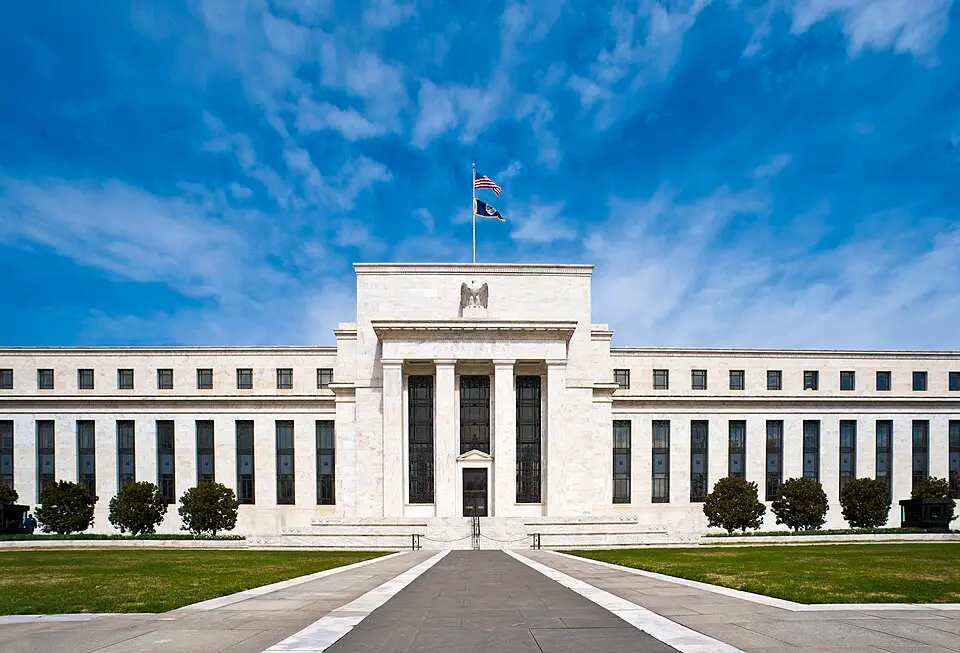
The Federal Reserve raised its benchmark interest rate Wednesday for the first time since 2023, reversing years of easing and holding steady as policymakers confront inflation that remains above their goal. The quarter-point increase puts the federal funds target range at 3.75% to 4%, with the effective benchmark rate around 3.9%.
The decision can eventually affect borrowing costs throughout the economy, including rates on credit cards, auto loans and mortgages. Consumers already dealing with elevated costs for housing, groceries and fuel could feel additional pressure if lenders pass higher financing costs along.
Federal Reserve Chair Kevin Warsh said inflation has remained too high for too long and indicated officials want clearer evidence that price increases are moving sustainably toward the central bank’s 2% target. The Fed also cited renewed global conflict and higher gasoline prices as factors complicating the inflation outlook.
The rate increase came despite President Donald Trump’s public calls for lower rates. Trump criticized the decision Wednesday, while Warsh emphasized the central bank’s responsibility to make monetary policy based on economic conditions rather than political demands.
Updated projections suggest Wednesday’s move may not be the last increase of 2026. Sixteen of 18 policymakers who submitted forecasts expect at least one additional rate hike this year, and Goldman Sachs now forecasts another quarter-point increase at the Fed’s October meeting.
The path ahead will depend heavily on inflation, employment, economic growth and energy prices. For households and businesses, the immediate takeaway is that the era of falling borrowing costs has paused and the Fed is again willing to tighten policy if inflation does not cool sufficiently.